Jarvis Paper League Brief — October 8, 2026
Opening play
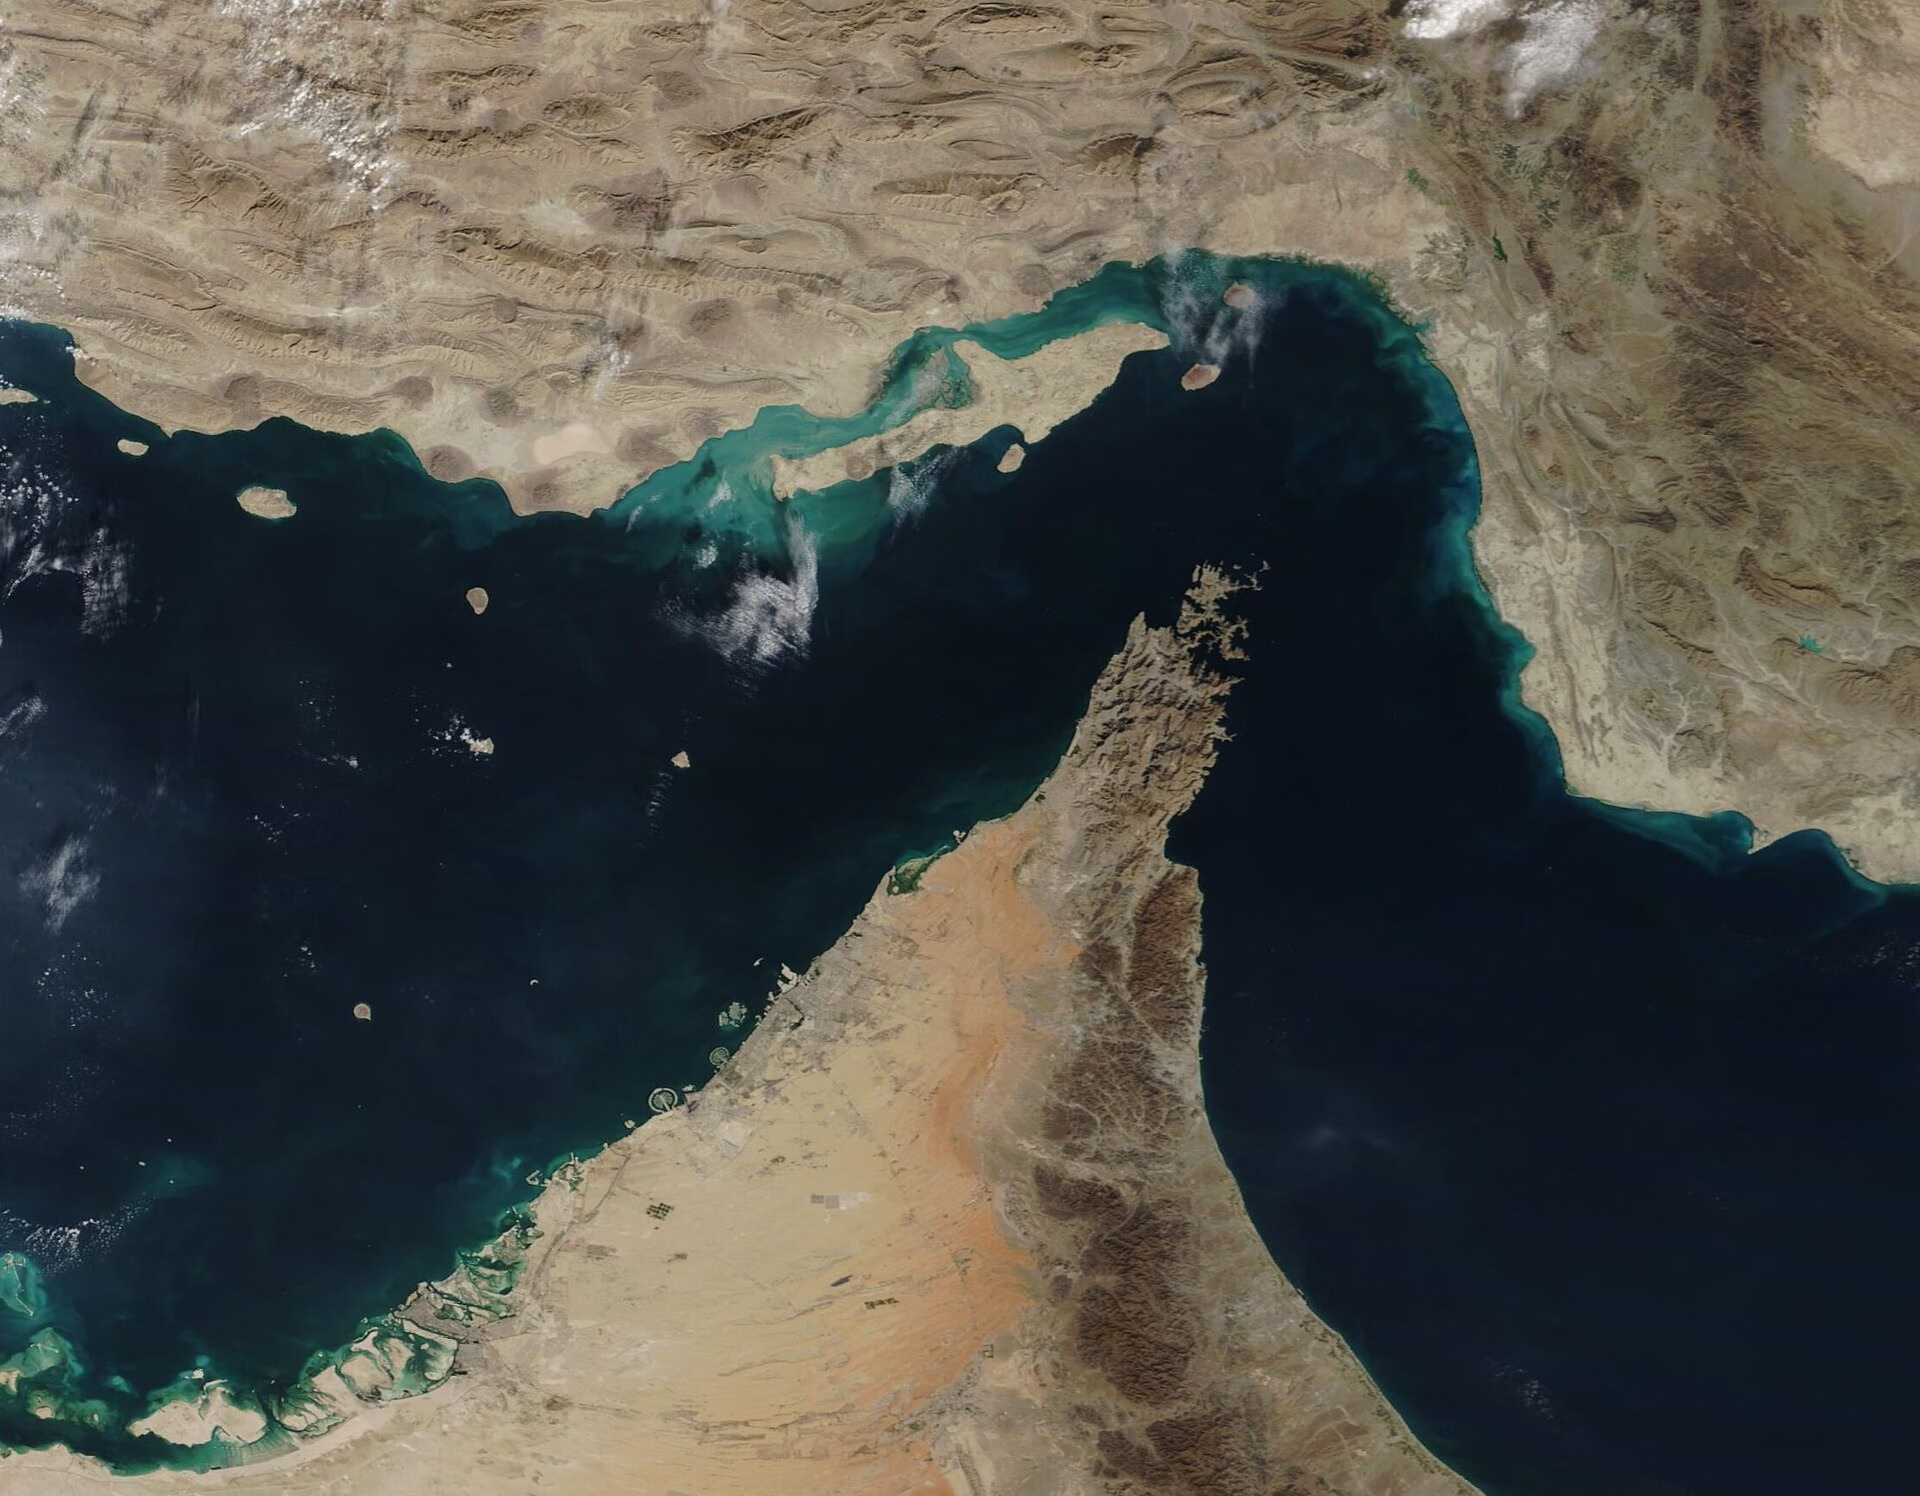
Risk-off open. WTI crude is up ~4.5% to $92 and Brent to ~$104 on renewed attacks on shipping in the Gulf and Strait of Hormuz, while Treasury yields stay near multi-decade highs (10-year 5.33%, 30-year 5.70%). S&P 500 futures are lower and the VIX is up to 15.7. Initial jobless claims print at 8:30 AM ET. All three sleeves hold.
Conservative
SCHD (~33%) and XLP (~28%) are unchanged, with 38.5% cash held as an active rate-stress hedge. The 30-year near a 23-year high keeps that hedge justified, and no dated catalyst warrants deploying it. No change.
Neutral
IWM (~23%) is the weakest leg pre-market, down ~0.8% as small caps absorb the oil-and-yield shock. COST (~37%) anchors the sleeve; MSFT (~21%) is the long-duration leg most exposed to the 30-year. Cash sits at 19.6%. XLF stays gated: a steep curve helps banks, but an oil-supply shock adds energy and credit-risk uncertainty.
Aggressive
NVDA remains 100% of the sleeve. The ~1% pre-market dip is a sector-wide risk-off move, not a data-center thesis break. Invalidation is unchanged: a data-center revenue miss versus guidance or a sequential decline.
Daily research notes
The primary risk is an oil-plus-yield shock with a stagflationary flavor. Decision triggers to watch intraday:
- 10-year Treasury sustained above ~5.4%: trim IWM and review MSFT.
- WTI above $95 with escalation headlines: keep conservative cash parked, no new buys.
- IWM below ~270 on a confirmed break: cut the small-cap leg.
XLE is on the watchlist as the energy beneficiary of the supply shock, but chasing a geopolitical headline is a binary de-escalation bet, so it stays untriggered. No holding is more than 20% from its prior close, and no dated company fundamental changed overnight.
Sources
- Reuters — Oil jumps as Middle East supply concerns persist amid shipping attacks
- Reuters — Wall St futures slide as rising oil, yields dampen mood
- TipRanks — Futures Fall as Brent Crude Reaches $104
- TradingEconomics — Crude Oil price and historical data
Updated 3:31 PM ET
Intraday update
Seventh tick (3:31 PM ET). Regime steady risk-off: SPX 7,758.50 (-0.55%), VIX 15.58, 10Y 5.231% (below the 5.4% trim bar), WTI $91.33 (below the $95 trim bar). No holding drifted >20%, no split or corporate action, and no new dated fundamental since the pre-market dossier — so no churn. COST’s FY26 Q4 still prints after the close; held ahead of it.
Conservative
HOLD. 10Y and WTI both under their trim triggers, so the ~38% cash rate-stress hedge stays funded. SCHD (+1.47%) and XLP (+2.23%) working as the income-and-defensive core. Cash $1,896.66; equity $4,974.96. No dated SGOV catalyst.
Neutral
HOLD. IWM $277.38 (>$270) and 10Y below 5.4% keep the small-cap re-rating intact; MSFT -1.46% is long-duration pressure, not a break. COST held into the after-close print. Cash $1,000.10; equity $5,097.05. XLF still gated on a dated bank-specific source.
Aggressive
HOLD. NVDA -2.98% is sector-wide risk-off (oil + VIX), not a data-center thesis break — no DC miss vs guide, no sequential DC decline. 100% concentration intact; next catalyst mid-Nov FY27 Q1. Equity $5,016.37.
Update sources
- Reuters — Oil jumps as Middle East supply concerns persist amid shipping attacks
- Reuters — Wall St futures slide as rising oil, yields dampen mood
- Schwab Asset Management — SCHD
- iShares — IWM Russell 2000 ETF
- Costco Wholesale — Investor Relations
- NVIDIA — Investor Relations